
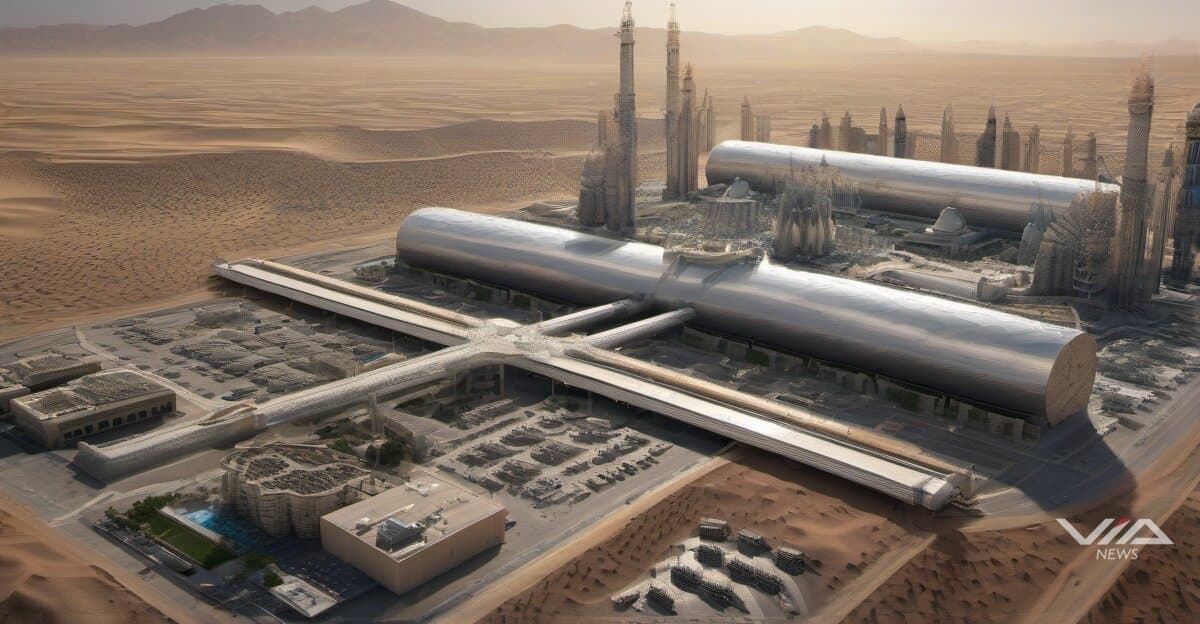
Saudi Arabia committed more than $15 billion to AI infrastructure investments across multiple cloud and chip providers within a 30-day window, marking one of the most concentrated national AI spending bursts on record. AWS, Google Cloud, AMD, and Nvidia secured deals in the spending cluster.
The Line project underwent a strategic repositioning from futuristic urban development to AI data center hub. The shift redirects billions in capital allocation from real estate construction to compute infrastructure, effectively converting stalled megaproject spending into tech-sector deployment.
The spending velocity exceeds typical sovereign technology investment pacing. Most nation-state AI programs phase spending across 3-5 years; Saudi Arabia's 30-day concentration suggests urgency to secure chip supply and cloud partnerships before potential export restrictions or capacity constraints emerge.
Three market implications crystallize from the capital deployment. First, chip manufacturers gain geographic demand diversification beyond US hyperscaler concentration. AMD and Nvidia can allocate production capacity to sovereign buyers with multi-year purchase commitments, reducing dependence on cyclical enterprise spending.
Second, MENA enterprise AI adoption likely accelerates within 6-12 months as in-region compute infrastructure comes online. Current latency and data residency barriers force regional enterprises to delay AI implementation; domestic data center capacity removes technical friction and regulatory obstacles.
Third, the spending establishes Middle East positioning in AI compute infrastructure competition. US and China currently dominate global AI processing capacity; Saudi investment creates a third geographic pole. This shifts AI sovereignty dynamics from bilateral US-China competition to multipolar infrastructure distribution.
The Line's conversion from real estate to tech infrastructure offers a template for other stalled megaprojects. Multiple Gulf states face similar challenges with delayed construction projects; pivoting to data center operations provides immediate capital deployment paths without multi-decade development timelines.
Cloud providers secure long-term regional anchor contracts that justify buildout costs in smaller markets. Google Cloud and AWS historically avoided major MENA infrastructure investment due to market size concerns; sovereign commitments change the capital deployment calculus.
The 30-day spending window timing coincides with heightened US AI chip export control discussions. Saudi Arabia's accelerated deal closure suggests anticipation of tightening technology transfer policies, frontrunning potential restrictions with contracted commitments.